 BBC News
Borrowing was £17.4bn last month, the second highest October figure since monthly records began in 1993.
Finito World
As the Chancellor resists calls to increase Capital Gains Tax, Britain confronts an awkward question: how do we reward work without discouraging wealth creation?
There is a curious contradiction at the heart of Britain’s economic debate. We want people to work hard, take risks, establish businesses, employ others and generate wealth. But we are less certain what to do when they succeed.
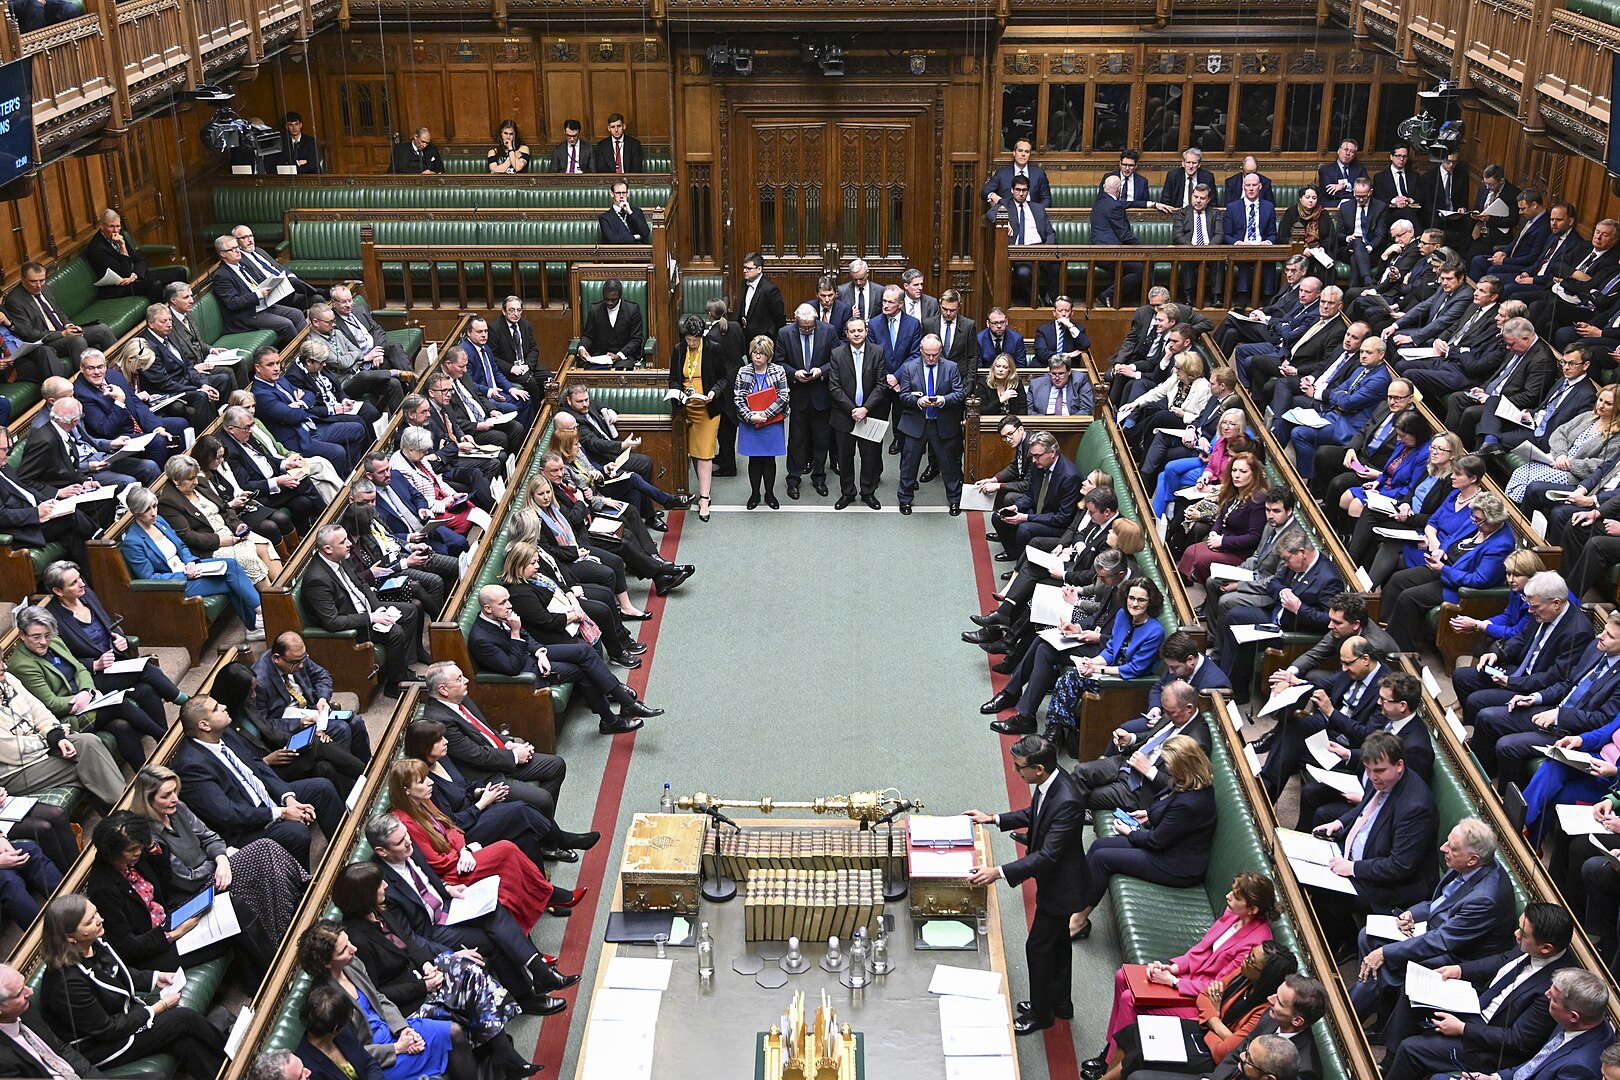
The latest argument concerns Capital Gains Tax (CGT), which is charged on profits made when certain assets, including shares and second properties, are sold. Ahead of his first Budget on 28 October, Chancellor John Healey has reportedly rejected calls from within Labour to increase the tax.
It is a decision with implications extending far beyond the bank accounts of the wealthy. At stake is something fundamental to Britain’s economic future: the relationship between enterprise, reward and opportunity.
The argument for raising CGT is not difficult to understand. Why should somebody earning £100,000 through employment face a higher marginal tax rate than somebody making the same amount through selling an investment? Is it fair that the tax system should apparently favour accumulated capital over the daily business of going to work?
For politicians concerned about inequality, this is a powerful question. Louise Haigh has argued that Britain should shift the tax burden away from employment and towards what she calls “unproductive capital accumulation”. Wes Streeting has similarly questioned a system which appears to penalise work.
But there is another side to the equation. Capital is not necessarily idle. It can finance a start-up, allow an entrepreneur to expand, support technological innovation or create the conditions in which somebody else finds employment.
A person who establishes a business, spends ten years building it and eventually sells it has not simply enjoyed an effortless windfall. They may have risked their savings, sacrificed their salary and worked considerably longer hours than their employees.
Nor are capital gains guaranteed. Investors can lose money, and a tax system which takes a substantial share of the upside may alter their willingness to accept the downside.
This is where the debate becomes especially relevant to the next generation.
Britain needs young people who want to establish companies, develop products and take the risks associated with entrepreneurship. It also needs investors prepared to back them.
But entrepreneurs and investors are unusually mobile. A business founder contemplating whether to establish a company in London, Dublin or elsewhere will inevitably consider the tax environment alongside access to talent, capital and customers.
The Treasury’s own modelling illustrates the difficulty. HMRC previously estimated that increasing the higher CGT rate by ten percentage points could actually reduce government receipts by £3.6 billion in 2028–29, once behavioural responses were considered.
That is not proof that every increase in CGT is counterproductive. But it is a reminder that taxation changes behaviour as well as raising revenue.
There is also an important distinction between different forms of wealth.
The investor who buys a property and benefits from rising house prices is not necessarily making the same contribution to economic growth as the founder who develops a successful engineering company employing 200 people.
A sensible tax system ought to recognise this difference. Equally, it should not allow income that is effectively payment for work to be disguised as capital gains simply to secure a lower tax rate.
The challenge is therefore not simply to decide whether capital gains should be taxed more heavily. It is to distinguish productive investment from passive accumulation, and genuine entrepreneurial risk from arrangements designed principally to minimise tax.
For younger people, the issue has another dimension. Many already face substantial barriers to accumulating capital of their own, particularly through home ownership. A country in which wealth is increasingly inherited rather than created risks undermining the very principle of opportunity.
That makes the case for rewarding work compelling. But it also makes the case for encouraging new businesses and new sources of wealth.
The two objectives should not be treated as enemies.
Healey has spoken of wanting Britain to become a country of wealth creation, with government policy encouraging confidence, investment and profit. It is a welcome ambition, provided it is accompanied by measures that allow more people to participate in that wealth creation.
Ultimately, the most important test of next week’s Budget will not be whether the Chancellor satisfies one faction of the Labour Party or another.
It will be whether a talented young person, contemplating the difficult decision to establish a business, believes Britain is a country in which ambition is worth pursuing.
And whether, if that business succeeds, the rewards will be sufficient to make the original risk worthwhile.